Your costs
Review the premium alongside deductibles, copays, coinsurance, and any benefit limits. A lower premium doesn't always mean lower total costs.
SELF-EMPLOYED HEALTH INSURANCE IN GEORGIA
A conversation about your coverage, your doctors, and your budget.
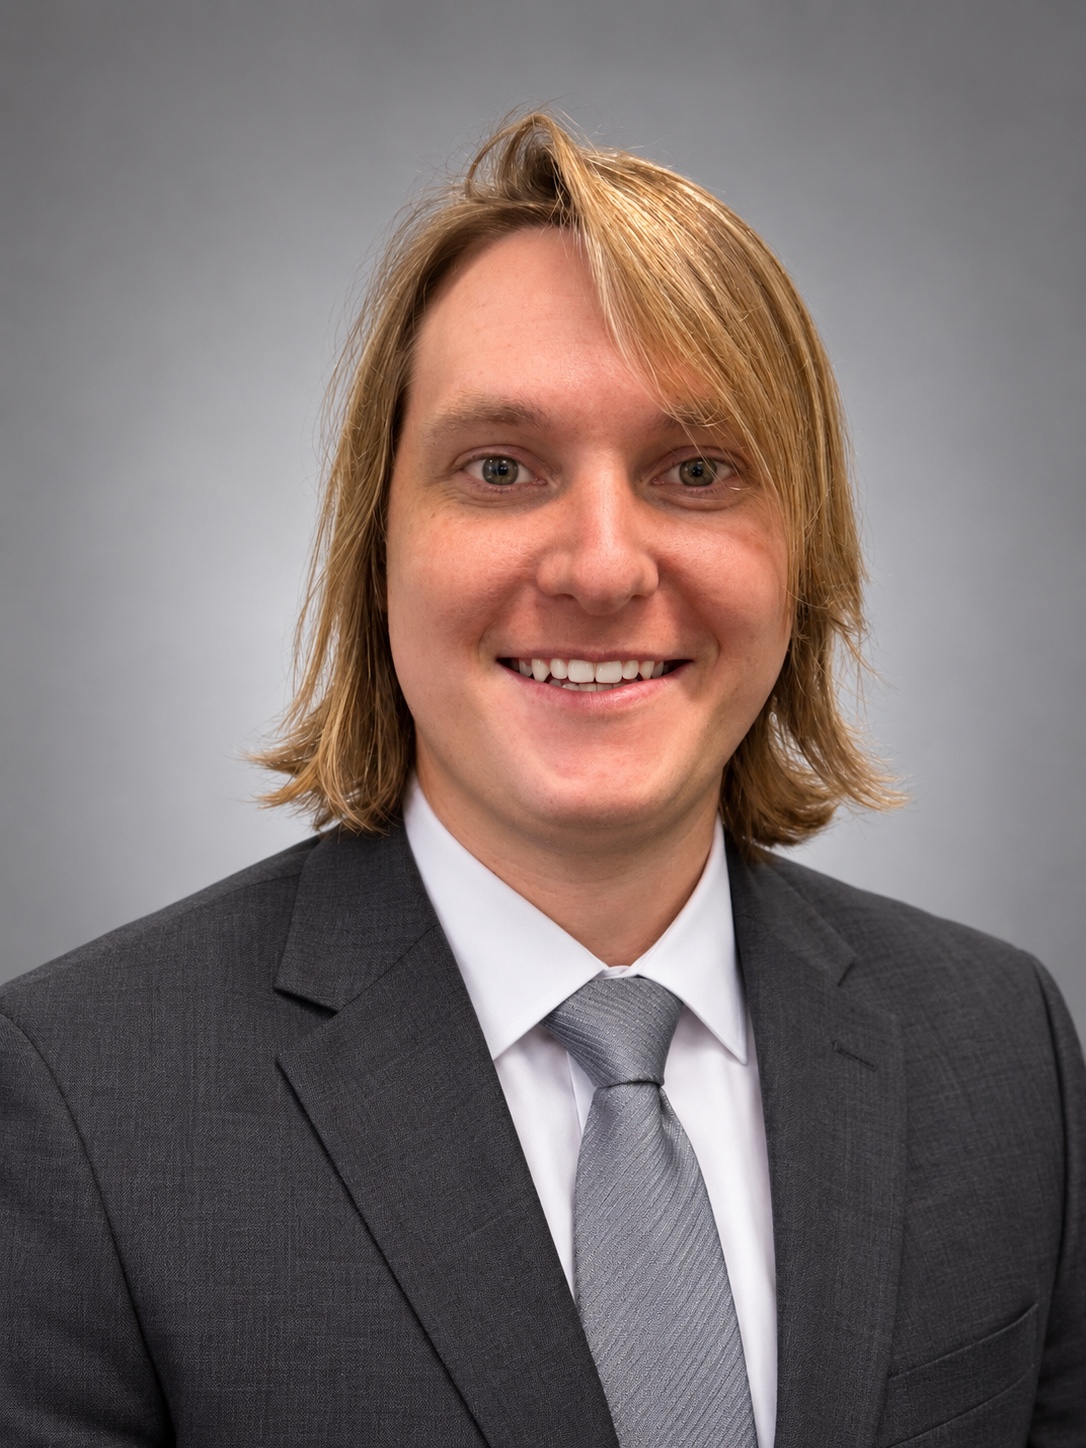
I'm Luke Sizemore. Based in Canton and Alpharetta, I help freelancers, contractors, and business owners throughout Georgia review available health coverage for themselves and their families.
Free consultation. No obligation to enroll.
START WITH WHAT MATTERS TO YOU
Review the premium alongside deductibles, copays, coinsurance, and any benefit limits. A lower premium doesn't always mean lower total costs.
Check the specific provider network and how the plan handles care outside it. We'll also review the prescriptions you want covered.
Talk through routine care, unexpected illness, and accidents—including what the policy pays, what it excludes, and what you may owe.
WHAT WE'LL TALK THROUGH
Maybe you're leaving a job, adding family members, or reviewing a premium increase. We'll start there and discuss the options Luke can offer.
Luke offers private coverage options directly. If an ACA Marketplace plan looks more suitable, he can refer you for Marketplace assistance.
Private coverage includes different types of products. We'll identify the type being discussed and explain how its benefits and protections compare with ACA major medical coverage.
FOR YOUR FIRST CONVERSATION
You don't need everything ready before calling. Share medical details privately during the consultation.
A FEW COMMON QUESTIONS
Yes. You can start a conversation whether you're a freelancer, independent contractor, or solo business owner. Available products and eligibility depend on your state and the plan.
No. PPO describes a provider network arrangement. It doesn't tell you which services a policy covers, what it pays, or whether it is comprehensive major medical coverage. We'll check those details separately.
Some private products Luke offers may require health questions or medical underwriting. Acceptance, exclusions, waiting periods, and benefits depend on the product. ACA Marketplace plans have different rules, including protections for pre-existing conditions.
We can review your options. Start dates, enrollment rules, and any approval requirements vary. Confirm the replacement coverage and its effective date before ending your current plan.
BASED IN CANTON & ALPHARETTA · SERVING GEORGIA
A phone or online conversation with Luke can help you understand the next step.
Bring your current plan summary, your preferred start date, and a monthly budget that remains workable in a slower month. Compare the actual contract alongside the quote. Separate health coverage from any benefits intended to help with bills while you are unable to work.
We start with who needs coverage, your ZIP code, your current monthly premium, and the date you need a plan. Then we review the private options Luke can offer, including the policy type, doctor network, benefits, and costs you may owe.
Example: A contractor leaving an employer plan should compare both the new monthly premium and the timing of replacement coverage. This is an illustration, not a quote or a promise of savings.
Working for yourself changes how you arrange coverage. Whether you freelance, subcontract, drive for a platform, or run a solo business, start with your ZIP code, who needs coverage, your budget, and your current coverage end date. Compare the actual policy type and benefits before choosing on premium alone.